While most people who care about this kind of stuff were focused on Treasury announcing that FinCEN would permanently remove the requirement for US companies to report beneficial ownership information to FinCEN, the Treasury inspector (TIGTA) dropped a short report that spoils its findings in the title: The IRS Did Not Provide Adequate Oversight to Ensure a Drug-Free Workplace [PDF]. Surely you guys have read plenty on the FinCEN news or can get it from more erudite sources than us, let’s talk about drugs instead.
Like all federal agencies, the IRS is required under the The Drug-Free Workplace Act of 1988 to maintain a drug-free workplace. TIGTA says this is especially important for tax administration because it goes without saying, you don’t want a bunch of maniacs on PCP handling taxpayer data.
A DFWP [Drug-Free Workforce Plan] is essential to the IRS in supporting employee health and safety, achieving the agency’s mission, and maintaining a productive workforce. The IRS has an obligation to eliminate illegal drug use from its workforce due to its tax administration responsibilities and the sensitive nature of its work.
We mention PCP because that’s one of the five drugs the IRS is supposed to be regularly testing certain employees for, along with marijuana, cocaine, amphetamines, and opiates. If they can’t tell someone’s on PCP by sight alone they have bigger problems.
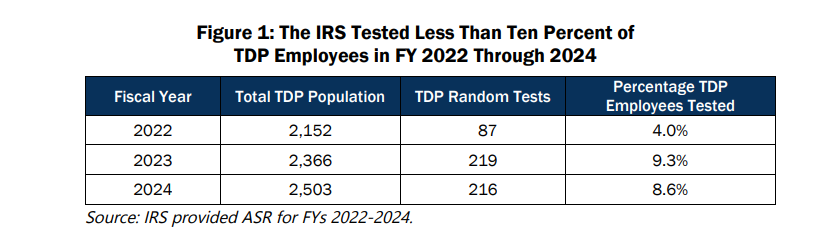
Under its own DFWP, the IRS is supposed to be randomly testing 10 percent of employees in sensitive positions like those with security clearances and people who have a work gun (which they call TDP, Testing Designated Positions) and applicants for Criminal Investigation positions when they’ve gotten far enough in the application process to have the job in the bag. Additionally, the IRS is supposed to test employees suspected of drug use…which they didn’t do at all from 2022-2024.
Said TIGTA:
However, frontline managers, in consultation with the HCO [Human Capital Office], did not refer employees for testing when they suspected employees were using drugs. Instead, they contacted our Office of Investigations (OI) to investigate the misconduct. For example, HCO management provided a list of five employees where drug use was suspected in Fiscal Year (FY) 2024; however, testing was not conducted. In addition, from October 2022 through April 2025, OI received investigative referrals for 78 employees based on allegations of illegal drug issues. The fact that these employees were referred to OI suggests management had enough of a concern and should have tested for reasonable suspicion.
These acronyms are getting out of hand.
So basically, instead of sending suspected drug users off to the lab to confirm suspected drug use first, managers fast tracked their suspicions to the Office of Investigations. TIGTA says the DFWP training managers get “does not provide sufficient information about reasonable suspicion testing” and instead only provides “a list of criteria the manager should consider for reasonable suspicion, such as a pattern of abnormal conduct, erratic behavior, or a non-negative test.” This training also “provides a conflicting message” as it tells managers to call OI if an employee snitches on another employee.
OI does not have the authority to drug test employees but they did complete some investigations. TIGTA shared that OI received 78 referrals during the covered period and some of them sound quite serious. We don’t know for sure but we do know this section of the report got the black bar treatment:
Once OI completes its investigation, it provides the results to the employee’s manager, who works with HCO management for final disciplinary determinations. From October 2022 through April 2025, OI received investigative referrals for 78 employees based on allegations of illegal drug issues. According to OI, an investigation should only be initiated if additional information indicates the drug issue occurred on government time, on government property, or was accompanied by other criminal activity (e.g., sale, purchase or possession of drugs on government property). Our analysis of OI’s case management system data identified that OI opened investigative cases for 22 IRS employees based on the 78 referrals for potential drug issues. After completing these investigations, OI referred 11 employees for prosecution; however, the Department of Justice declined to prosecute them. According to OI, the remaining 11 employees were not referred for prosecution because OI did not develop evidence of criminal activity.
For the 11 employees that were referred and subsequently declined for prosecution, IRS management determined the following actions were warranted:
3 employees received disciplinary actions including suspension, reprimand, or written counseling.
3 employees resigned or retired.
For the remaining five employees, management did not take action as follows:
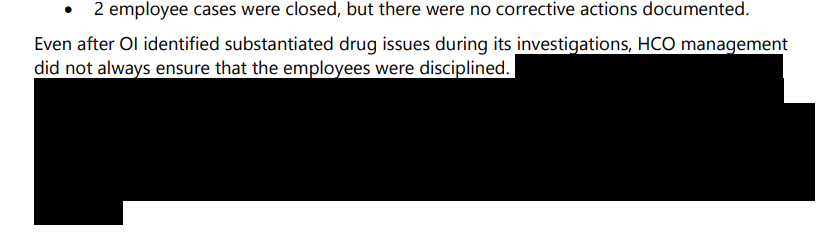
3 employee cases were closed without action or withdrawn.
2 employee cases were closed, but there were no corrective actions documented.
On the random drug testing side, the IRS didn’t meet its 10 percent target, though they came close in 2023.
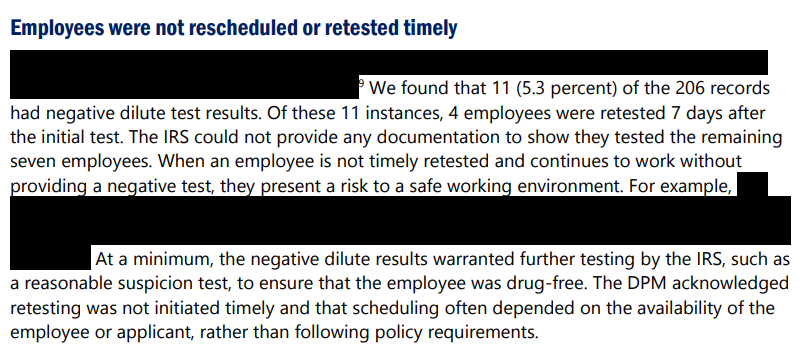
We get black bars again on the part about retests. Not sure what they were covering up here but we’re dying to know since it’s a paragraph on negative dilute test results. For those of you who don’t know, negative dilute means they suspect the testee drank an obscene amount of water to get the drugs out of their system before the test. It doesn’t always mean there was nefarious intent, only that it’s possible they attempted to get drug concentrations low enough to be undetectable by a drug test by chugging water.
Lastly, TIGTA found that the DFWP manager (DPM) is tracking all of this with spreadsheets, a practice considered suboptimal by GAO internal control standards:
The DPM manually tracks drug testing activities using spreadsheets, email correspondence, and third-party database records. Although the records are maintained in a centralized location, we determined that this centralized location lacks automated controls and continues to rely on manual processes. According to the Government Accountability Office’s Standards for Internal Control in the Federal Government, effective internal controls require management to establish and operate a system that provides reasonable assurance that the organization will achieve its objectives for operations, reporting, and compliance. As it is currently structured, the DFWP does not provide the assurance it is meeting its mission as evidenced by the inaccurate depiction of a drug-free workforce in the ASR [Annual Summary Report] and not meeting the minimum requirement to test 10 percent of the TDP employees.
Full report, along with TIGTA recommendations, can be found here.
We should note that for the purposes of celebrity tax issues, Joe Francis does not qualify since he’s technically a “douche” and not a “celebrity”. Also, since the $33 million-ish lien just up and disappeared (we’re assuming that Lucifer is somehow involved) he’s off the hook.
Anyhoo, so being tardy on taxes seems to be a common occurrence but Suge seems to be going for the tardiest of the tardy. He has managed to avoid paying a tax lien, originally filed in 2003, for his 1996 tax return. TMZ is reporting that the lien was re-filed in January and that he owes $6,578,696.31.
TMZ is also reporting that in child support papers filed by Suge’s baby mama, it was revealed that his net income is only $1,207 so paying this lien is going to need some kind of resurrected 2Pac comeback somethingorother.
The blog Baller Status also reports that last month “several personal items he had tucked away in storage were auctioned off to the highest bidder after he failed to pay the storage fees. Belongings such as furniture, TVs, and even a large photo of himself with the late Tupac Shakur were sold.”
So whenever you’re feeling a little down about your own dire personal financial situation or think about your crappy pay, just remember that you could be Suge Knight.
Okay maybe that’s a stretch but we’re guessing, what with all the rebellious employees, that the IRS is a tough place to work. Because of this high stress environment, normally rational people may jump to conclusions about otherwise harmless religious symbols.
A judge recently dismissed most of the legal claims of a former IRS revenue agent that wore a kirpan to work. Continued, after the jump
Web CPA:
The revenue agent, Kawaljeet Kaur Tagore, sued the IRS after she was fired in July 2006 for wearing a “kirpan” to the IRS office in Houston…The blunt knife is traditionally worn in a curved sheath and is supposed to act as a reminder of a Sikh’s duty to protect the weak and promote justice for all. Tagore’s supervisor objected to the dagger, even though she claimed it never set off the metal detector in her building, and she was told to work from home.
How can you not get behind protecting the weak and justice for all? Still, Tagore was fired after refusing to wear a knife with a shorter, 2.5 inch, blade and returning with the 3 inch knife even though, as the original story reports, she had sharper items in her office, including her scissors.
Tagore filed suit earlier this year:
claiming that the government’s conduct violated both the Religious Freedom Restoration Act of 1993 and Title VII of the Civil Rights Act of 1964. The defendants included the IRS, the Treasury Department, the Department of Homeland Security, former Treasury Secretary Henry Paulson, former Homeland Security Secretary Michael Chertoff and several of Tagore’s supervisors.
Bad news is that the judge threw out the some of the Title VII claims but good news is that the one against T. Geith still remains. We’ll continue to follow this story if new developments happen to drop on another painfully slow news day. IRS Dagger Carrier’s Claims Partly Dismissed [Web CPA Debits & Credits]
Presumably this means celebrities too! That is, until the IRS can show that it’s actually an effective means of collection and not so ‘hard core.’
Olson has accused the agency of relying too heavily on an automated “one-size-fits-all approach.” She said the agency misguidedly files liens against people who have no money and no assets.
“Absent data that show liens make a meaningful contribution to revenue collection and especially in this economy, I find it unacceptable that the IRS continues to torment financially struggling taxpayers in this way,” Olson wrote in a news release accompanying the report.
Perhaps Olson has a point but then Robert Snell over at Tax Watchdog might not have a job and we’d hate to see that happen. The guy is like Raisin Bran™ on the celebrity tax deadbeat.
One thought on “The IRS’s Drug-Free Workforce Plan Tested Positive For Low Effort”
Recreational MJ is legal in many states now and (as I understand it) it will test positive up to 30 days later which has rendered preexisting testing regimes difficult. Someone can legally do a couple of joints on a Friday afternoon after work, show up for work on Monday perfectly sober, take a whiz quiz two weeks later and pop positive. How do you go about enforcing this anymore?
Comments are closed.
Before you go!
Are you Looking for a fresh accounting career opportunity?
Going Concern now has thousands of open accounting jobs.


Recreational MJ is legal in many states now and (as I understand it) it will test positive up to 30 days later which has rendered preexisting testing regimes difficult. Someone can legally do a couple of joints on a Friday afternoon after work, show up for work on Monday perfectly sober, take a whiz quiz two weeks later and pop positive. How do you go about enforcing this anymore?