It’s bad enough that Wealth Squads are going to be kicking down doors left and right but now this?
Still doesn’t quite top California’s budget misfire but keep trying Albany!
N.Y. Assembly Looks at Millionaire’s Tax [FOX via Tax Policy Blog]

When accounting goes unaccounted for
It’s bad enough that Wealth Squads are going to be kicking down doors left and right but now this?
Still doesn’t quite top California’s budget misfire but keep trying Albany!
N.Y. Assembly Looks at Millionaire’s Tax [FOX via Tax Policy Blog]
That accountant is Ren Carlton, CPA, CSMC and “native Michigander.” Although Ren is hesitant to broach the subject because, “this information can be abused to defraud investors and cheat on taxes.” Who knew?!?
Despite that caveat, Ren has decided that sharing this information is too critical to be kept to himself, “I have decided that legas is a critical skill for attracting investors and lenders, as well as satisfying the occasional customer or vendor requests.”
Okay then! So if we understand correctly, the rationale here is that cooking the books is sort of like drinking alcohol. In moderation, it’s fine and sometimes even the right thing to do but if you abuse it, you start making an ass out of yourself and probably some bad decisions that could lead to, ya know, jail.
But wait, do you really even know what “cook the books” means? You may be under the cockamamie notion that it’s a bad thing. Well, it’s not and Ren explains it for us:
Cooking the books (also known as creative accounting and earnings management) are euphemisms referring to accounting practices that may follow the letter of the rules of standard accounting practices, but certainly deviate from the spirit of those rules. They are characterized by excessive complication and the use of novel ways of characterizing income, assets, or liabilities and the intent to influence readers toward the interpretations desired by the authors. The terms “innovative” or “aggressive” are also sometimes used.
See? Cooking the books just doesn’t follow the “spirit of those rules,” it’s not breaking the rules. Strangely enough, Ren’s definition is strangely similar to this Wikipedia entry for creative accounting:
Creative accounting and earnings management are euphemisms referring to accounting practices that may follow the letter of the rules of standard accounting practices, but certainly deviate from the spirit of those rules. They are characterized by excessive complication and the use of novel ways of characterizing income, assets, or liabilities and the intent to influence readers towards the interpretations desired by the authors. The terms “innovative” or “aggressive” are also sometimes used.
Cooking the books, creative accounting – they’re the same right? Close enough, anyway. Now that the semantics are out of the way, what other words of wisdom can we get from Ren? How about an example of acceptable book cooking? Say, revenue recognition:
One example of cooking the books is acceleration of revenue recognition. This tactic is used to recognize revenue before it is considered earned by GAAP (Generally Accepted Accounting Principles). Methods for accelerating revenue include recognizing sales that are not yet earned or complete. Another method is to book sales that are actually earned in another period (e.g., recognizing January 2011 sales on your 2010 income statement). Flagrant abuse of the Revenue Recognition Principle includes backdating sales and fabricating fictitious sales.
How are you going to impress that bank with your revenue numbers if you ram in some revenue from a future period? What if you need another investor to help you reach the next stage of your business? It’s your God-given right to present them with phony numbers in order to get them on board. This is America, people. Don’t let the spirit of GAAP hold you back!
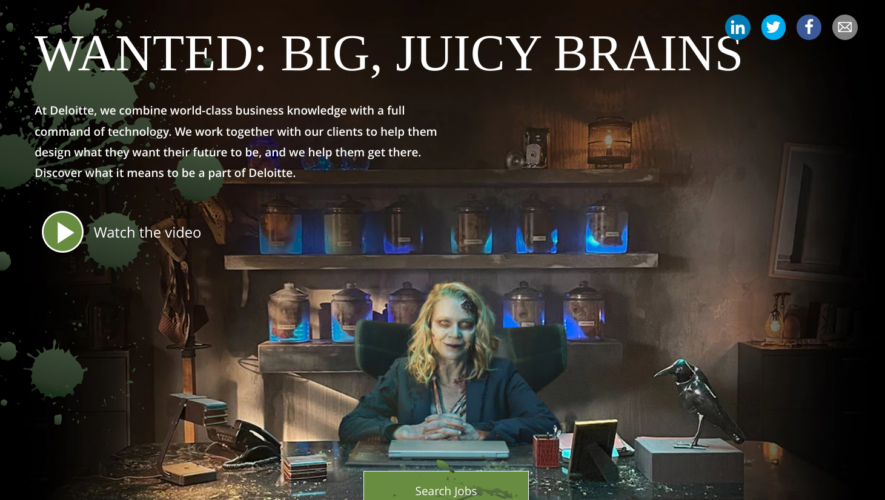
We always suspected there was something odd about people who work for Deloitte, now we […]
 On Friday, Grant Thornton had a firm wide call to discuss several things including layoffs, compensation, and grab-bag questions.
Headcount Reductions – Steve-o believes that the worst is over and that “restructuring efforts are substantially behind us.” If there happens to be additional “headcount transitions” it will be to refine operations or part of the no He went on to say that the people that are GTers now will, “in very large part,” remain GTers. So can we assume the action in Cleveland and Chicago was the last of it?
Compensation: GT seems is making big push towards a “pay for performance” model for its employees which means compensation adjustments will focus on top performers (“5s” in GT world) and market based adjustments (i.e. keeping up the Joneses) won’t be happening. SC cited a downward trend of salaries in the accounting profession based on a survey that GT does with Mercer (sounds convenient) for the phasing out of market adjustments. He said there might be some exceptions to this.
The size of the merit adjustments have not yet been determined because it all depends on how well 1) GT performs through the end of the year and 2) individual performance. Chip said that enough people were belly aching about the old adjustment system that a change was warranted. This will be implemented slightly for this fiscal year (can’t get all Darwin about it 3/4 of the way through the fiscal year) and will be the main methods for next year and going forward.
Bonuses: SC cleared this whole issue up saying that it has not been determined if bonuses will be paid this year. It all depends no the firm’s performance in the final quarter of the fiscal year. He did say that he’s pre-tay, pre-tay, pre-tay optimistic about the firm “being in a position to pay bonuses” but they’re still crunching the numbers so there’s no telling if it will be a mini-windfall, pocket change, or a set of steak knives.
Not to worry though, as the top performers will certainly get something if everything goes well at the firm overall.
This “new” focus on pay for performance seems kind of familiar since all the firms assign rankings to employees (with their own bizarro methodologies) and are paid accordingly. It makes you wonder if those that fall in the meaty part of the GT curve will get such a small adjustment that it will be another twist on the forced ranking trend amongst accounting firms.
Steve-o then shared his general optimism about the direction of the economy and what it means for the firm, a few recent client wins, yada yada yada. He also updated everyone with some very vague details on the firm’s new strategy “Unleashing Our Potential” that will be rolling out in the next fiscal year. Basically all non-partners will have the chance to drop their $0.02 on this strategeroy very soon but other than that we couldn’t tell if the new strategy involved a lunar landing or full-scale assault on financial reporting fraud.
Last but perhaps most importantly, Steve-o admitted to enjoying the Masters very much, however he was quite clear that he was less than thrilled to see KPMG on Phil’s lid. We’re sure it’s nothing personal against Phil but those may be fightin’ words directed straight at Johnny V.